
Quick tips for building your retirement confidence
The Employee Benefit Research Institute’s 2025 Retirement Confidence Survey finds that majorities of Americans report a positive outlook for retirement—67% of workers and 78% of retirees feel confident they will have enough money to live comfortably throughout retirement. We have some tips to help you feel more confident that you’re doing all you can to pursue your financial goals.
Don’t set it and forget it
The amount you need to save, how much you can plan on from Social Security, etc., are based on estimated numbers that will change over time. Revisit your financial goals and assumptions at least once a year or when major life changes happen so you can make adjustments to your savings strategy.
Think smaller
Instead of looking at your retirement goal as one big number, try looking at your anticipated monthly income need. This will make it easier to view along with your monthly expected Wisconsin Retirement System pension and Social Security estimate. It can help make your planning process more manageable, realistic, and less daunting.
Take the match and stretch to the limit
If your district employer offers a match in their 403(b) program, be sure to take it—it’s free money. And if you can max out your contributions, do it. You may even be permitted extra catch-up contributions once your turn 50. In addition, certain employees who are ages 60 to 63 may qualify for a super catch-up limit in 2025, if allowed in your plan. Learn more about contribution limits.
Use free tools and resources
Member Benefits offers a plethora of financial information and tools to help you plan ahead. Visit our learning center to access articles, calculators, eBooks, and much more.
Prioritize your future
Life will throw financial challenges at you, but it will likely also throw you some opportunities. When you get a raise, pay off a debt, or get a tax refund, that may be a good time to put extra savings into your retirement.
8 timeless principles of investing
1. Focus on what you can control
Market movements, business decisions, economic events, politics, interest rates—many factors can influence the performance of your investments. Instead of worrying about events that are out of your hands, focus on what’s within your control.
2. Put time on your side
Financial markets have rewarded long-term investors. Compound growth may help bring about higher returns over time. Keep in mind, however, that past performance does not guarantee future results.
3. Tune out the noise
News cycles driven by fear, uncertainty, and doubt can challenge even the most disciplined investor. Some headlines spark anxiety, while others try to goad you into chasing the hottest fads and trends. Although we live in an era of seemingly infinite data, information overload can cause you to (perhaps unwisely) reconsider investment decisions.
4. Don’t try to time the market
Market timing is the strategy of trying to predict future market movements to time buying and selling decisions. When markets are rallying or pulling back, it can be very tempting to try to seek out the top for selling or the bottom for buying. The problem is that investors usually guess wrong, missing out on the best market days. Another approach is to focus on time in the market, which may let you ride out the natural market cycles and focus on your long-term goals.
5. Understand risk
Market risk—or the risk of your portfolio losing value due to factors such as changing market conditions—isn’t the only type of risk to be concerned about. Personal risks, such as longer lifespans and rising health care costs, mean that you need to consider a variety of factors as you prepare for retirement. Understanding risk as it relates to your time horizon and investing goals is critical to a financial strategy.
6. Avoid the emotional roller coaster
Emotional decision making can lead to the wrong decision at the wrong time. A DALBAR study found that while the S&P 500 returned 6.06% for the 20-year period ending in 2019, the average investor fared worse, seeing a return of only 4.25% during the same period. Emotional decision making was one of the factors that contributed to the difference in performance.1
7. Don’t procrastinate
The sooner you begin investing, the longer your money can work for you. Let’s look at two hypothetical investors, Jack and Jill. When Jill turns 50, she starts contributing $25,000 a year to an account that earns a hypothetical 6%. After 10 years, she stops making payments. Jack puts off his investing program. At age 60, he begins putting $25,000 a year into an account that earns a hypothetical 6%. Though both have contributed equal amounts, Jill has the magic of compound interest working for her. When they both reach age 70, Jill’s account balance is nearly twice the size of Jack’s.2 Learn how compound interest may help you save more over time.
8. Delegate the details
The financial professionals at Member Benefits can help you create a customized portfolio strategy that’s built around your unique goals. Although we can’t control markets, we can help you use them to pursue your long-term financial goals. Contact us for an appointment.
1-800-279-4030
weafa@weabenefits.com
Source: FMG. All financial advisory services are offered through WEA Financial Advisors, Inc., an SEC registered investment advisor.
1. TheBalance.com, November 22, 2021 (most recent data available). S&P 500 measures the performance of 500 of the largest public companies in the U.S. You cannot invest directly in an index.
2. This example is for illustrative purposes only and does not represent an actual investment or combination of investments. Annual contributions are made at the beginning of the compounding period. This hypothetical example does not reflect taxes or any fees. Past performance does not guarantee future returns.
Smart strategies for a secure retirement
If you want to start stepping into retirement, consider these resources to help you along the way.
yourINCOME PATH™
A suite of options Member Benefits offers to help turn your retirement savings into income. This includes a range of flexible withdrawal options to meet cash flow needs, required minimum distribution support, qualified charitable distributions, and more—all at no additional cost.
Financial calculators
Our free financial calculators include an Investor Suitability Profile Questionnaire, retirement savings and planning options, Social Security and Wisconsin Retirement System links, and more. The Impact of Withdrawals savings calculator can be helpful when planning a retirement savings withdrawal strategy.
Retirement Income Analysis
A focused retirement planning service for those within 10 years of retirement. A financial planner will help you define your retirement goals, evaluate your financial position today, and determine whether you are on track to meet your goals.
eMoney
Those saving with Member Benefits’ 403(b) can use this free online platform to build their financial strategy and request a consultation to collaborate in real time with our financial advisors.
And more FREE resources available in our Learning Center.
Stepping in to retirement
Are you close to retiring? Financial security in retirement doesn’t just happen. It takes planning, commitment—and money. Unfortunately, only about half of Americans have calculated how much they need to save for retirement (Department of Labor). And the closer you are to retiring, the more you need to have a plan in place.
Retirement planning involves setting goals and developing strategies to help protect your financial future. The earlier you start, the better. But if you’re nearing retirement and haven’t started yet, don’t worry—it’s never too late.
First step: Determine what kind of retirement you want
Retirement looks different for everyone. Do you want to fully leave the workforce, work part-time, or take a sabbatical between jobs and continue working? Consider your ideal lifestyle and financial needs.
Second step: Build your plan
- Decide on what age you want to retire. This will help you determine if you need to save more to reach your goals.
- Set realistic spending expectations. Many aim for 70–80% of their pre-retirement income, but this can vary. Consider the longevity of your portfolio to determine how much you can withdraw each year. With longer life expectancies, you’ll want to ensure your savings lasts throughout retirement.
- Factor in health care expenses. Medical costs are often one of the biggest financial challenges in retirement. While exact needs are hard to predict, plan for how you’ll cover both acute and long-term care expenses once you’re no longer working.
Third step: Maximize late-career opportunities
Your late 50s and early 60s are often peak earning years, making it a great time to boost your retirement savings. Take advantage of catch-up contributions—those 50 and older can contribute an extra $1,000 to an IRA or $7,500 to a 403(b) or 457 plan in 2024. (Learn more about contribution limits.)
Keep a close eye on your asset allocations. With less time to recover from potential losses, it’s important to assess the level of risk you’re comfortable with.
Finally, focus on eliminating debt and assessing your retirement income sources to be fully prepared for when you choose to retire.
Final step: Get help
Planning for retirement is not a simple process. Many things need to be taken into consideration. It’s OK to feel overwhelmed or to have questions.
That’s why it’s great to have a partner you can trust to help you with your financial planning. As a participant in Member Benefits’ programs, you have access to our financial advisory services, which can help you refine your strategies as retirement approaches. We also offer a free program called yourINCOME PATH to manage your required minimum distributions, and provide various online resources as well.
Contact us for support. We’re here to help you.
P. S. Pick up some smart strategies for a secure retirement.
Financially savvy millennials have a Roth IRA…here’s why
No taxes (on earnings or qualified withdrawals)
That’s right. Your retirement savings account grows absolutely tax free and you won’t owe a dime when you start taking withdrawals as long as your follow the IRS rules. This is because Uncle Sam takes taxes out before you invest it. It’s like prepaying your taxes. The frosting on this cake is that you are not taxed on any account earnings. Hard to believe, I know. Don’t question it, just go with it.
Just $20
That’s all you need to start a Roth IRA with WEA Member Benefits. Other providers may require $500 or $1,000 to open an account, but we think you should be able start with whatever you can afford. A comfortable retirement is an expensive proposition. But, starting sooner even with as little as $20 per pay period can make a significant difference in your financial future.
Flexibility
A Roth IRA is also more flexible than other retirement savings. Although the purpose of a Roth IRA is to save for retirement—long-term savings—access to your contributions is much easier than say in a 403(b) or 401(k) account. However, withdrawing from your account is not recommended because your money needs to be in the account so it can grow, but if you have an emergency and have no other options, it’s nice to know it’s there.
PLEASE NOTE:
Contributions is italicized in the previous paragraph for a reason. Withdrawing any of your earnings before age 59½ will trigger a tax bill on the money, plus you’ll have to pay a 10% penalty. So you won’t want to do that. Unless…you want to tap your Roth for either of these two reasons and qualify.
- To buy your first home. If you use your Roth IRA for a first-home purchase, in addition to using your contributions for the down payment, you can also withdraw up to $10,000 of earnings tax- and penalty-free if the account has been open for at least five years. Even if you fail the five-year test, the withdrawal will still be penalty-free, but you will have to pay tax on the withdrawn earnings. The $10,000 limit is per person, so couples could withdraw up to $20,000 of earnings if they each have a Roth IRA.
- To pay for college. Many parents don’t know whether to save for retirement or their child’s college tuition. Retirement always wins that debate. There are lots of finance options for a college education; for retirement, not so much. A Roth IRA is a great way to cover plan for either. Focus on your retirement now, saving as much into a Roth as you can. And as your finances allow, consider opening a 529 plan, like Wisconsin’s Edvest. When the tuition bill comes due, you can see where you’re at.
Pump up your retirement savings
The 403(b) is a great way for public employees to save for retirement. As a Wisconsin public school employee, you need WRS, Social Security, AND personal savings for your retirement plan to be complete.
Take a few steps to help you decide how much you would like to save in your 403(b).
- Get our free 403(b) enrollment guide and learn more about 403(b) options and benefits, savings tips, choosing an investment strategy, determining your risk, and more.
- Review contribution limits to help you evaluate how much you’re putting towards retirement and whether you’re saving enough to meet your future goals.
- Decided to change the amount you’re saving? To update your SRA, please contact your school district business office for their most recent SRA, download our SRA form, or if your district allows, update your SRA online through yourMONEY.
If you have questions or need more guidance, give us a call at 1-800-279-4030 or schedule a personal consultation.
Understanding stable value investing
If you’ve been watching some of the money market rates at banks and credit unions recently, it may be tempting to transfer all or some of your retirement money to one—or several. After all, some of them have a higher interest rate than you’ve seen in several years, so it would make sense, right? But when it comes to your retirement savings, short-term thinking isn’t necessarily a good strategy. The fact is that successful fixed-income investing remains a long-term game.
Before you make any financial moves you may regret, we want to help you understand the fundamentals of stable value investing, the current state of the interest rate market, and what you need to know to make sound investment decisions. This includes the role that stable value funds like the Guaranteed Stable Investment* (GSI) have in your overall portfolio. It will also help answer the question, “Why is the GSI rate lower than what I can get at a bank right now?”
Slow and steady
Retirement accounts are meant for long-term investing, and so is the GSI. Transactional accounts, like money market accounts offered by banks and credit unions, are meant for short-term saving strategies. This also makes them more sensitive to changing interest rates, which can cause them to change their rates more quickly.
It may help to think of a quick analogy. Say there are two boats heading toward a destination. The GSI is like a large ocean liner and transactional accounts are like a sailboat. Over a long journey, the ocean liner handily outpaces the sailboat and is less affected by wind movements (interest rates). During the journey, if both boats had to make a sharp turn to correct their course, the sailboat would be capable of making that turn quickly, while it would take the ocean liner some time to make that maneuver. It might temporarily appear that the ocean liner is off course and that you’d get to the destination faster in the sailboat. But once the liner completes its turn, it will again outpace the sailboat on the way to the destination.
If you think of the destination as your retirement goal, it becomes clearer. Take a look at the graph below. Historically, stable value funds have provided a return above short-term bank savings products. Last year is the first time in many years money market funds outperformed stable value funds. Why? According to Vanguard, “The Federal Reserve has been raising interest rates at the fastest pace in history to combat the highest inflation seen in decades. Both money market and stable value funds are focused on capital preservation and secondarily on providing current income. But they feature several important differences. Historically, because of the longer-term nature of stable value fund holdings, they have usually returned a premium over money market funds: 1.33% on average annually over ten years and just over 2.00% since 1990. Generally, periods of money market funds outperforming stable value funds are limited in nature and unsustainable.”**

It’s clear that this inversion is unusual—and likely temporary.
GSI vs money market accounts
The GSI and money market accounts are very different from one another. Unlike money market accounts, stable value funds like the GSI are not built to pivot quickly along with changes in interest rates. Stable value fund crediting rates typically take longer to respond to changes in market interest rates—both during times of rising and falling interest rates. This is a benefit to participants when interest rates are dropping or at a sustained low level, because participants continue to benefit from a higher crediting rate for a longer period.
The other side of the coin is that when market interest rates rise—especially when they rise rapidly—the crediting rate takes time to respond. Rates were low for a long time, so the investments within the GSI portfolio still carry those lower interest rates. This will change as those investments reach maturity.
Obviously, money market accounts can sometimes pay higher interest rates than other types of savings accounts such as stable value. We’ve been asked at times why Member Benefits doesn’t offer a money market account. The short answer is that when offering a stable value fund, there are certain “competing funds” that may not be offered in the investment lineup, such as a money market fund. Stable value could be removed from the program to make room for a money market option, but as the charts and graphs throughout this article demonstrate, that would not be a wise decision when saving for the long-term.
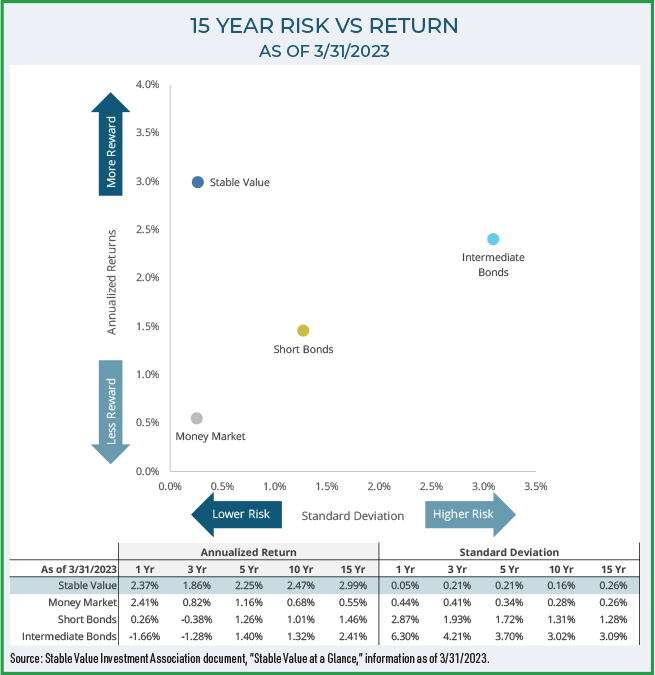
Consider the graph above. An analysis of the last 15 years shows that stable value funds provide a higher annualized return than money market funds—with exceptionally low volatility.
Mike Driscoll, Managing Director of Sheridan Road and an Accredited Investment Fiduciary, has over 40 years of experience in the financial industry. Mike is also a longtime consultant to WEA Member Benefits. He sums it up by explaining, “The rapid rise in short-term rates since March of 2022 was the largest increase in rates since the 1980’s. The stable value asset class performed as expected and delivered on its primary investment objective of preserving investor capital and providing a competitive yield versus other low-risk alternatives. As interest rates stabilize, we expect to see stable value fund crediting rates gradually reset higher as they reflect the new elevated level of interest rates.”
Stay on course
We are in an unusual interest rate environment, so it can be tempting to make decisions based on short-term circumstances. But unfortunately, if you decide to move out of our 403(b) or IRA program, you may not be able to come back.
Navigate your retirement journey with the big picture in mind and don’t let temporary circumstances dictate your long-term decision-making.
*Interest is compounded daily to produce yield net of Empower’s administrative fee of 0.60%. EAIC is compensated in connection with this product by deducting an amount for investment expenses and risk from the investment experience of certain assets held in EAIC’s general account.
** Vanguard, Perspectives, May 18, 2023; Morningstar data as of 3/31/23.
Facts about Roth IRA contribution eligibility
The 2024 Roth IRA contribution limit is $7,000 for those under age 50 and $8,000 for those 50 and older.
IRA contribution limits include the combined limit for both the traditional and Roth IRA. For example, if you are under age 50 and you contribute $5,000 to a traditional IRA this year, you can contribute up to $2,000 to your Roth IRA, if eligible.
Your Roth IRA contribution limit, or eligibility to contribute at all, is dictated by your income (household modified adjusted gross income (MAGI)).
Roth IRA income requirements for 2024
| Filing status | Modified adjusted gross income (MAGI) | Contribution limit |
|---|---|---|
| Single individuals | < $146,000 | $7,000 |
| ≥ $146,000 but < $161,000 | Partial contribution | |
| ≥ $161,000 | Not eligible | |
| Married (filing joint returns) | < $230,000 | $7,000 |
| ≥ $230,000 but < $240,000 | Partial contribution | |
| ≥ $240,000 | Not eligible | |
| Married (filing separately) | < $10,000 | Partial contribution |
| ≥ $10,000 | Not eligible |
Depending on your MAGI and tax filing status, you are either eligible to contribute to your Roth IRA up to the full IRA maximum, contribute only a partial amount, or contribute nothing at all.
You can’t contribute more to your Roth IRA than your earned household income. If your earned income is less than the contribution limit, then your personal IRA contribution may be limited by your earned income.
Spousal contribution limits may be limited by your spouse’s income if you have no income yourself and are contributing to a spousal IRA.
Always consult a tax advisor if you have questions around your eligibility to contribute.
Moving money myths
Myth #1: You have to move your money out of WEA Member Benefits because…
Despite what you might hear, you DO NOT need to move your money from your 403(b) or IRA with Member Benefits if you:
- Retire or leave your job to take another job (even if it’s not in education).
- Turn (insert any number) years old.
- Move out of Wisconsin.
Myth #2: You won’t have access to your 403(b) funds in retirement because it is in an “annuity” (tax-sheltered annuity).
Our program has flexible withdrawal options without surrender periods (the amount of time an investor must wait before withdrawing funds from an annuity without penalty). Often individual annuities or insurance company annuities have surrender/maturity periods that are many years long (sometimes up to 12 years). Ours doesn’t.
Myth #3: There are fees to get funds out of your account upon retirement.
Nope! Member Benefits does not charge transactional fees or surrender charges even if you move your money out. (Mutual fund management and redemption fees apply.)
Have questions? Contact us at 1-800-279-4030.
This is the second article in our series. Read more:
- Moving money matters (first article)
- Moving money concerns (third article)
Create or change IRA contributions online
When you log in to your IRA retirement account through yourMONEY, you have the option of starting or changing your contributions in the portal.
You can choose between a one-time or a recurring contribution. A one-time contribution is a lump sum contribution and may take 7-10 days to process, while a recurring contribution is a monthly scheduled contribution that is automatically pulled from your bank account on or around the 15th of each month.
It’s simple and straightforward to do:
- After logging into your yourMONEY portal, click on the Plans header.
- Hover your mouse over ‘Contributions’ and select either ‘One-Time Contribution’ or ‘Recurring Contribution.’
- Fill in the necessary information, including the name of your financial institution, routing number, and your account number.
You can modify or cancel your contribution choices at any time. Cancel or modify a recurring contribution by the 13th for it to be effective the same month.
To learn more about managing your IRA contributions in yourMONEY, view a quick video or call us with any questions at 1-800-279-4030.