
Financial literacy is for everyone
In our Fall 2024 issue, we highlighted Wisconsin educator Kerri Herrild and her work in helping pass a law requiring high school students in our state to take a financial literacy course.
We applaud the decision and know it will make a positive difference in many young people’s lives. But we also want to acknowledge something just as important—that financial literacy isn’t just for the young.
At Member Benefits, we hear members talk about how they wish they knew more when they were younger. But the good news is that there’s always something new to learn. It’s never too late to become more financially knowledgeable, no matter what your age.
With that in mind, we’ve put together some helpful financial tips and resources. We hope it will make it easier to get you started on your financial journey…or to continue on your path of learning.
So now that your students are set to become more financially literate in the coming years—how about you?
Budgeting
Building a budget calls for an investment of time up front and requires you to face the good and the bad of your financial situation. But the pay off and benefits are long lasting.
Writing a budget helps you set up and achieve goals by:
- Establishing priorities.
- Giving you permission to spend.
- Helping you save money for long- and short-term needs.
- Preparing you for financial emergencies.
Use our budget worksheet and financial calculators as a guide, and/or schedule a financial planning consultation to help you get started.
Managing debt
Spending more than you earn on a consistent basis can build debt quickly. Having a budget can help you prevent the problems that come with that.
Being in debt has a BIG impact on financial wellness by affecting your credit score, paying higher interest rates, making it harder to get a loan, etc., as well as taking a toll on your mental and physical health.
If you’re carrying too much debt, devise a plan to pay off the highest interest debt first. Paying off your outstanding bills has many benefits—it improves your credit score, reduces stress, and increases your financial security. If you need some help, contact one of our financial advisors. And use our online debt calculators as a resource.
Saving
The phrase “pay yourself first” can be a powerful savings strategy. It means you pay into your own savings and investments before anything else.
There are three types of savings goals you may want to achieve, which will change depending on your age. For example:
- Short-term (0-5 years): Emergency fund, vacations, start a family.
- Intermediate term (5-10 years): New car, new home/condo, college fund.
- Long-term (10 years or more): Retirement savings (IRA, 403(b), etc.).
An emergency fund is critical—there will always be surprise financial situations that pop up in daily life. Start with a goal of saving at least three months worth of expenses in your emergency fund. Six months is even better if you can do it. Consider setting up a recurring transaction to place money in your emergency fund each month. If you need to, take it slow and just save $20 per paycheck, increasing as you are able.
Saving for retirement earlier than later gives you a huge advantage by utilizing the power of compound earnings over time. Setting up automatic contributions into your retirement account using payroll deduction or electronic funds transfer can make saving easier to do.
You’ll also want to save enough for a potentially long retirement—it’s easy to forget the fact that we are living longer, often into our 80s and 90s. Depending on when you retire, you could be looking at 30+ years outside of the workforce.
Investing
Though many people think of them as the same thing, saving and investing are different.
- Saving money has a shorter-term horizon and a low risk of losing value, but generally has lower returns over time. It commonly utilizes savings accounts, CDs, or money market accounts to save and preserve assets.
- Investing has a longer-term horizon and comes with risk, including loss of principal, but also has the potential for higher returns—though they are never guaranteed. It is a strategy used to save for long-term goals, such as retirement or saving for college, and utilizes stocks, bonds, mutual funds, and ETFs.
The idea of investing can be intimidating for some people. However, being a good saver is far more important than being a skilled or knowledgeable investor. Simply getting started is key. In fact, waiting to invest can make a significant negative impact on how much you’re able to save over time.
Investing can help grow your wealth by potentially:
- Providing you with retirement savings.
- Helping you get out of a financial predicament.
- Becoming an additional source of income.
Before you start investing:
- It’s important to balance the potential gains with the risk involved.
- You’ll want to be in a good financial position to invest, such as having manageable debt and an adequate emergency fund, so you can ride the ups and downs of the market without having to withdraw from your investments.
- The earlier you start to invest, the better due to compound interest. But it is never too late to start investing.
Protecting
Many people don’t think about insurance as a way to conserve money. But if you don’t have the right coverage, you put yourself at financial risk.
For example, umbrella (personal liability) insurance is an often misunderstood coverage because many people assume their basic insurance policy offers them adequate protection. However, you may be surprised at the situations in which you may need umbrella insurance—your dog bites a neighbor, someone slips on your sidewalk, or your teen throws a party while you’re gone and one of the guests gets an Operating While Intoxicated (OWI) on the way home. An umbrella policy provides extra protection for you as well as other members of your family.
In general, we suggest you consider three principles to help find the right insurance coverage for your needs:
- Buy the right amount of protection for your situation.
- Buy more liability protection rather than less.
- Choose the highest deductible amount that you can comfortably afford.
While many companies offer auto, home, and umbrella insurance, ours is the only one created exclusively for public school employees like you. Set up a consultation and we’ll review your coverage so you can compare.
And if you have any recreational vehicles or classic cars, make sure they’re covered, too. We can help with that.
Credit score
As we mentioned earlier, debt can negatively affect your credit score. FICO (Fair Isaac Corporation) credit scores are used by financial institutions and credit card companies to determine whether you can get a loan and at what interest rate. It uses information from a consumer’s credit report to indicate the ability to repay amounts borrowed.
Information in your credit report is used in various ways. For example, credit card companies may give you a more favorable interest rate and a larger line of credit with a higher score. Potential lenders, landlords, insurance companies, and even some employers use your credit score to help make decisions about you. Companies use different sets of factors related to your score to make their decisions, so it’s safe to say that the higher your score, the better.
Employee benefits
According to the Employee Benefit Research Institute, only about 55% of workers say they understand their workplace financial benefits well. Taking advantage of all the benefits offered to you at work can help you boost your wealth as well as your job satisfaction. For example, if your district offers a match in their 403(b), take it—it’s free money.
If you’re not clear on the workplace benefits available to you, contact your human resources department or district office. Make sure you know about any post-employment benefits that may be offered as well.
Tax benefits
Another way to safeguard your wealth is by taking all the tax credits and deductions you are qualified for each year. Common ones to watch for may be based on your income, on paying for higher education, or on putting money into a retirement or health savings account. As an educator, you may be eligible to deduct expenses for classroom materials. Be sure to consult your tax advisor to know what you qualify for.
Borrow smart
It can be tricky, but one key to building financial security is to borrow only what you need. You are likely to need a loan to purchase a house or car, or to pay for college education, for example. But ask yourself questions first: Just how expensive of a house do you need? Do you really need a premium packaged car? The less you borrow, the more you have to spend on other financial goals, material goods, and life experiences.
Get support
The foundation underlying Member Benefits’ offerings of products and services is one of financial education. It underscores everything we do. So please turn to us with your questions, learn from our resources, and consider our program options. We are here to help every member become financially secure.
Saving by the decade – Finish strong
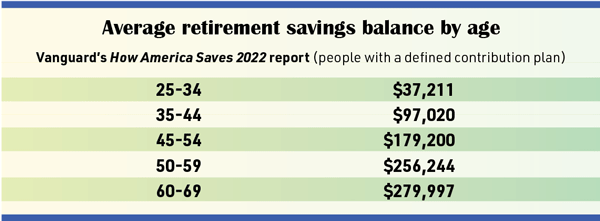
Building that nest egg for your daily needs can be a challenge. And for many, the idea of saving for retirement is often a ‘tomorrow’ idea—until it becomes ‘soon.’ But the longer you wait to save, the more it can cost you. We share some general guidelines to make saving a bit easier by the decade.
Your 60s: Finish strong
This is a time to set yourself up to enjoy retirement. According to Social Security’s life expectancy calculator, the average age someone age 65 can expect to live to is 84.2 for males and 86.8 for females. However, one out of three males and one out of two females who are in their mid-50s today will live to age 90 (Society of Actuaries Age Wise Longevity Infographic Series, 2019). So you need to plan for at least two decades of retirement, perhaps even longer.
Financially, it’s time to decide on when to take Social Security and to make your final decisions regarding WRS. Your estate plans, life insurance, health insurance, and long-term care insurance policies should all be in order.
In this decade (or before), you may be visited by other companies regarding your retirement accounts. Be sure you understand all costs involved, including advisory fees or annuities you may be locked into before you make a decision to move your money.
If you’ve had several jobs, may want to consider consolidating accounts with Member Benefits to minimize costs. Our financial advisors can help you evaluate retirement plans, help you shift your risk, or do a comprehensive Retirement Income Analysis to define your retirement goals, evaluate your financial position today, and determine whether you are on track to meet your goals and create a withdrawal strategy.
You’ll also want to understand and plan ahead for the annual RMD you have to start taking out of your retirement account once you reach RMD age (unless it’s a Roth IRA).
Member Benefits can help turn your retirement savings account balance into income during retirement with yourINCOME PATH, a suite of solutions and support we offer that includes a range of flexible withdrawal options to meet cash flow needs, RMD support, qualified charitable distributions, Roth conversion strategies, and more. There are no additional costs for this service if you have an account with us.
Revisit your plan often
None of our suggestions need to be limited to a specific decade of your life—many of them apply to other decades and across your career. Of course, depending on what age you are now, things may change quite a bit by the time you reach future decades. Be ready to tweak your plan, keep yourself informed over time, and visit your plan often.
If you weren’t able to start saving in early in life, remember—no matter what decade you’re living in, it’s never too late to start.
<<Part 4, Catch up
>>Return to Part 1 of our series on saving in your 20s.
Sources: Citizens First Bank, Forbes, Vanguard.
Your actual situation may be different depending on future rates. No guarantees are expressed or implied. If you choose to invest in the 403(b) or IRA programs, fees will apply. Consider all expenses before investing. Mutual fund management and redemption fees may apply.
Saving by the decade – Catch-up if needed
Building that nest egg for your daily needs can be a challenge. And for many, the idea of saving for retirement is often a ‘tomorrow’ idea—until it becomes ‘soon.’ But the longer you wait to save, the more it can cost you. We share some general guidelines to make saving a bit easier by the decade.
Your 50s: Catch-up if needed
For many people, this tends to be a good earnings decade, so take advantage of it. Now is the time to figure out what you may be missing and catch up if you’re behind. Both the 403(b) and the IRA allow an age 50 and over catch-up option (learn about contribution limits). Some districts may also offer a 15 years of service catch-up provision in their 403(b) plan. Contact your district office to learn more.
If you can accomplish it, your debt should be paid off except for a mortgage and potentially your cars. Keep up your emergency savings to equal three to six months of salary.
It may be hard to hear, but you also qualify for some senior discounts in this decade—why not embrace them?
If you don’t have a life insurance policy yet, now is a good time. You may also want to consider long-term care insurance. Most costs for extended care needed during recuperation from strokes, accidents, illnesses, and operations are not covered by health insurance or Medicare. And it may be less expensive to start a policy while you are relatively young. Associates of Clifton Park is our long-term care partner and can tailor a policy to cover many circumstances.
Now is also a good time to start learning about your benefits with the Wisconsin Retirement System (WRS), Social Security, and Medicare. Download our free 20 WRS FAQs eBook to get started.
As you get closer to retirement, you may want to start considering where you might live and what you will do for work, personal insurance, and health insurance. Our financial planning advice options can help you evaluate your current investment portfolio or explore whether you’re on track for retirement. And if you are close to retirement, our financial planners can help you define your retirement goals, evaluate your financial position, and create a plan to turn your retirement savings into income during retirement.
<<Read Part 3 of our series on saving in your 40s.
>>Read Part 5 of our series on saving in your 60s.
Sources: Citizens First Bank, Forbes, Vanguard.
Your actual situation may be different depending on future rates. No guarantees are expressed or implied. If you choose to invest in the 403(b) or IRA programs, fees will apply. Consider all expenses before investing. Mutual fund management and redemption fees may apply.
Saving by the decade – Stay on track
Building that nest egg for your daily needs can be a challenge. And for many, the idea of saving for retirement is often a ‘tomorrow’ idea—until it becomes ‘soon.’ But the longer you wait to save, the more it can cost you. We share some general guidelines to make saving a bit easier by the decade.
Your 40s: Stay on track
Continue to pay down debt. If there have been any changes in your life, be sure to review your life insurance policies and check the beneficiaries on all of your policies and accounts.
If you haven’t done it yet, it’s a good idea to get your estate plan in order to make things easier on your family.
You may be able to add a flexible spending account (FSA) or health savings account (HSA) from your employer to your savings mix to help you pay for qualified medical expenses.
Make an inventory of your possessions to be well-prepared in the case of a serious insurance claim. You can take video or photos, or download our free Personal Property Home Inventory eBook.
However you save for retirement, be sure you know the underlying costs involved. Program costs vary between providers and impact your savings over time. Keep your money in your account working for you rather than being consumed by product or advisor costs. Learn more about fees in your retirement account.
Explore our financial coaching options at to learn more about fees, start some initial estate planning, make sure your savings plan aligns with your goals, and more.
If you have a 403(b) account with WEA Member Benefits, we offer you an interactive wealth management tool called eMoney at no additional cost. This tool also helps our financial planning staff provide you with the best strategic advice available. Visit eMoney to fill out an interest form.
<<Read Part 2 of our series on saving in your 30s.
>>Read Part 4 of our series on saving in your 50s.
Sources: Citizens First Bank, Forbes, Vanguard.
Your actual situation may be different depending on future rates. No guarantees are expressed or implied. If you choose to invest in the 403(b) or IRA programs, fees will apply. Consider all expenses before investing. Mutual fund management and redemption fees may apply.
Saving by the decade – Increase your savings
Building that nest egg for your daily needs can be a challenge. And for many, the idea of saving for retirement is often a ‘tomorrow’ idea—until it becomes ‘soon.’ But the longer you wait to save, the more it can cost you. We share some general guidelines to make saving a bit easier by the decade.
Your 30s: Increase your savings
During these years, you may want to save up for a home. You should also continue to build your emergency fund and tackle student loans and debt.
If you’re starting a family, you’ll want to make sure they’re properly protected by reviewing your personal insurance policies to ensure they have the appropriate coverage to protect your family and belongings. Consider adding umbrella insurance and life insurance in the mix.
Life insurance is an important part of your family’s financial stability and well-being. If anyone depends on your income, they would likely struggle if you were to pass away. It’s a simple answer to a very difficult question: How will my loved ones manage financially if something were to happen to me? Member Benefits offers a variety of life insurance options through our partner, Associates of Clifton Park. You can get a comparison quote online without providing any personal information.
If your budget allows, consider saving for your children’s academic future with a 529 college savings plan such as Wisconsin’s EdVest plan. These plans provide certain tax advantages, and grandparents and friends can contribute, too!
As a younger person, time is on your side in terms of the market and your future ability to generate income. While it can be a challenge to balance out family expenses, you should still put aside as much as you can towards your retirement. You may want to increase your after-tax options by adding a Roth IRA account to your savings plan, which has more investment options and no required minimum distributions (RMD) during your lifetime. A Roth IRA also has more flexibility with respect to accessing your money prior to retirement.
Member Benefits can help you make educated financial decisions based on your situation, investment objectives, and risk tolerance. Use our Investor Suitability Profile Questionnaire to help you determine what kind of investor you are.
You may want to consider scheduling a financial planning consultation to discuss budgeting, saving, or a net worth analysis. Learn more about our financial coaching options.
<<Read Part 1 of our series on saving in your 20s.
>>Read Part 3 of our series on saving in your 40s.
Sources: Citizens First Bank, Forbes, Vanguard.
Your actual situation may be different depending on future rates. No guarantees are expressed or implied. If you choose to invest in the 403(b) or IRA programs, fees will apply. Consider all expenses before investing. Mutual fund management and redemption fees may apply.
Saving by the decade – Get started
Building that nest egg for your daily needs can be a challenge. And for many, the idea of saving for retirement is often a ‘tomorrow’ idea—until it becomes ‘soon.’ But the longer you wait to save, the more it can cost you. We share some general guidelines to make saving a bit easier by the decade.
Saving money…it’s more than just spending less so you can build up your bank account. Saving more for your daily living needs and to meet your financial goals includes managing your budget, eliminating debt, strategizing your investments, protecting your assets, and more.
And just as importantly, it also includes preparing for your retirement—even if that seems like a long time from now. Not enough of us are doing so. According to the U.S. Census 2021 Survey of Income and Program Participation, among working-age individuals (ages 15 to 64), only 47.8% of men and 43.5% of women owned a retirement account—meaning over half do not have a retirement account at all. Baby Boomers (ages 56-64) were the most likely to own at least one type of retirement account, while Gen Z members (ages 15-23) were least likely to own a retirement account…but to their advantage, if they choose to use it, they also have the most time to accumulate additional retirement savings.
How you spend, save, and invest in every decade of your life has a significant impact on your financial well-being and financial future. Consider these tips to help manage your finances at every age and work toward a more secure retirement.
Your 20s: Get started
This is often the decade where you’ll make the least money—but it’s a great time to start building a budget, establishing your credit, and bulking up your emergency fund. Use our free budget form to help you start some good financial habits.
Contribute as much as you can to a 403(b). Your district may offer an employer match where the district matches your contributions—it could be fifty cents on the dollar up to a certain level, a flat amount, or many other types of options. As an added bonus, a match effectively increases your income without increasing your tax bill, since you pay no taxes on matching contributions until you withdraw them in retirement. If you’re not putting money into your 403(b) and there’s a match, then you may be leaving money on the table. Make it a goal to at least meet the match your district offers, if available. If you can afford to save more, even better!
Saving for your future now, even if it’s not a lot, gives you ample time to capitalize on the power of compound interest. The benefit of compound interest is that it grows over the years, earning interest on interest on interest. Even small contributions now can make a significant difference in your future nest egg.
>>Read Part 2 of our series on saving in your 30s.
Sources: Citizens First Bank, Forbes, Vanguard.
Your actual situation may be different depending on future rates. No guarantees are expressed or implied. If you choose to invest in the 403(b) or IRA programs, fees will apply. Consider all expenses before investing. Mutual fund management and redemption fees may apply.
The beauty of budgeting
Having a budget is a key component of any financial plan. You can’t have a plan without having a clear understanding of what money is coming in as well as what is going out—and where it’s going.
When people feel overwhelmed by financial issues and unsure of what to do, a budget is the place to start. It requires an investment of time up front and it requires you to face the good and the bad of your financial situation. But the pay off and benefits are long-lasting.
Writing a budget helps you set and achieve goals by:
- Setting priorities.
- Keeping you from spending more than you earn.
- Giving you permission to spend.
- Giving you a plan to eliminate debt.
- Helping you save money for long- and short-term needs.
- Preparing you for financial emergencies.
Developing a budget can be a empowering experience that can help you take control of your finances. Explore our helpful tools and resources in the article sidebar to get started on your own budget strategy.
Planning for the effects of inflation in your retirement plan
In 2021, inflation increased by 7%—its highest point since 1982 (Bureau of Labor Statistics). So $1 at the beginning of last year was worth around $0.93 at the end.
While inflation is an important consideration, it’s just one of several risks you need to manage in retirement. Protecting yourself in retirement consists of:
- Creating an income plan that factors in inflation over the course of many years.
- Adjusting for inflation spikes that may affect your short-term budget.
While it’s not time to panic, you shouldn’t ignore it, either.
Here are a few steps to consider to help protect your savings.
Save where you can. Even modest steps can add up. Being flexible about your travel or where you live can also help.
Continue investing. Consider keeping some of your savings in stocks for long-term growth.
Pay off debt. Eliminating debt should be a top priority in retirement.
Consider working. Every dollar you earn in retirement is a dollar you don’t have to withdraw. Go part-time or explore a second career as a buffer. It may be an interesting opportunity you hadn’t considered.
If this has you feeling a bit anxious, keep this in mind: Having WRS as a public school employee is a great advantage for you, along with Social Security’s built-in cost of living increases and your personal retirement savings.
Need some guidance?
Explore our financial planning options. Our expanded services give you even more choices to meet your individual needs. We’re here to help.
The above content is not a recommendation to invest. Please consult your financial planner to determine the path best for your financial well-being.
Sources: Kiplinger, Forbes Advisor.
Sarah’s garden of financial knowledge
Sarah Campbell has been sowing seeds since 2009. She has watched those seeds sprout, grow, and in some cases, produce. The seeds Sarah sows are the seeds of financial literacy.
Her passion for financial literacy sprouted in her second year of teaching when she made discoveries about how to cultivate enthusiasm for this important topic in her students. She struggled her first year, teaching content straight out of the textbook. “The kids didn’t care,” she told us.
But after taking courses at the National Institute for Financial and Economic Literacy during summer break, everything changed. The experience showed her how to engage students by making the information personal and real.
Over the last 13 years her methods have changed—going deeper and broader—to reflect the needs of students and to keep up with advancements in technology and the financial world. But she is still teaching Personal Finance at Wisconsin Dells High School (WDHS) with great determination, and her responsibilities have grown, giving her more opportunities to promote financial literacy. But what does financial literacy mean?
Digging deep
For Sarah, it’s not enough to simply understand financial concepts and best practices. It’s much bigger than that. Being financially literate, she says, is about looking at your financial life from many angles—like how you fit into the economy, understanding your role in managing your finances, what your decisions mean to you and those around you, and taking a hard look at what you want your life to be and understanding how finances play into your ability to achieve goals. Sarah likes the term financial independence—it plays like a drum beat in her classes. “It’s the ultimate goal. Regardless of how financially literate you are, the end game is financial independence.”
But Sarah digs deeper still, helping her students look inward at their financial beliefs and why they hold those beliefs. “Understanding the financial mindset that drives decisions, even those that don’t seem financial at the time, can be really useful and necessary.”
If it sounds a little philosophic, that’s because it is. Taking responsibility for your own financial position has been her emphasis from the start, telling students to ‘own’ their future. Her message was and still is, “It’s up to you to determine what you want your life to be like and how you are going to make it happen. No one else can do that for you.”
To incorporate her philosophy in the classroom, Sarah created characters they follow through the units. “I give them a variety of back stories and future plans to reflect the diversity in my class. We analyze their situations, create solutions, discuss back-up plans, and plot out future plans for them.”
And she says a change in scheduling has played to her advantage. Back in 2009, Sarah’s personal finance class lasted nine weeks. Not a lot of time to cover so much ground. That changed to 18 weeks after the district moved away from a block schedule. “I still have around 65 hours, but now it’s spread out into shorter chunks. For me, it’s a win. The longer time frame allows for more time for students to process the information and practice self-observation, and I have more time to build trusting relationships,” she explains.
“Understanding the financial mindset that drives decisions, even those that don’t seem financial at the time, can be really useful and necessary.”
Born to sow
“Without a doubt, imparting financial knowledge is what drives me in the classroom, and not just in the Personal Finance course. I incorporate a lot of financial literacy into my other classes AND my academic support period.” Her additional responsibilities give her plenty of opportunities. She serves as the MATC Dual-Credit Instructor for Accounting and Microsoft Office. Dual-credit courses, she explains, allow eligible students to complete their high school graduation requirements while earning college credits at no cost to the student. “But becoming the Youth Apprenticeship Coordinator was the biggest change to my duties. This program integrates school-based and work-based learning to instruct students in employability and occupational skills.” In essence, students get to “try on” possible career paths without the expense of post-high school courses. Sarah sees it as a time of discovery with very real financial implications.
“I had a student work for two years as an auto mechanic, and during his last semester realized he wasn’t happy. He was relieved that he didn’t waste two years of time and money after high school only to learn it wasn’t for him. Another student, interested in business, was able to complete an accounting program at MATC in a year and a half and begin working. It saved him both time and money,” she adds.
WDHS gives students a head start
Wisconsin Dells is one of just 800 school districts in the nation where a one-semester personal finance course is required for graduation. Currently, just one in six students across the nation graduate with a decent financial literacy education, and only 10 states guarantee at least a one semester course in personal finance before graduation. Wisconsin is not among them—leaving it up to the district to decide if and how they want to do it.
“High school is really the best time to get it into their head,” Sarah explains, “while they are on the cusp of major decisions that could determine the trajectory of their lives.”
Data supports Sarah’s hypothesis. Studies show that graduates of high schools with guaranteed financial education are 21% less likely to carry a balance on a credit card while in college1 and are less likely to fall prey to high-cost predatory loans (such as payday loans) than their peers without guaranteed financial education.2
Statistics like these, financial literacy advocates say, show that providing financial education offers a great return on investment.
“Regardless of how financially literate you are, the end game is financial independence.”
Reaping the harvest
Sarah also has a lot of personal examples where the seeds she sows yield good results.
“Just last summer a student stopped by on her way to college, literally packed up in her new (used) vehicle purchase. She was excited to tell me that although the dealer encouraged her to take a six-year loan to reduce monthly payments as a college student, she was adamant on a four-year loan because she did NOT want to have the loan follow her after college. She was so proud of herself,” Sarah shares.
Another time, she saw a student at a baseball game. “Always the jokester—he told me he bought a brand-new truck and stretched out the loan to seven years! But then he began laughing and said, ‘just kidding, I knew better than that.’ In reality, he purchased a used truck for a price that fit into his budget with a four-year loan.” Then his friend jumped in. “He said he got his first credit card and likes to max it out, then make only the minimum payments when he remembers. He broke out laughing too, and assured me he only uses it for gas and pays it off every month. They knew these things were the exact opposite of what I taught them and they didn’t want to disappoint me. Not only did they apply the concepts to make responsible choices, but they wanted me to know it, too. And, they enjoyed hassling me a little,” Sarah chuckles.
In her own backyard
Sarah’s ultimate goal of financial independence for her students is also something she strives for personally and teaches in her home.
In 2009, when her daughter was just three years old, Sarah was intentional about financial literacy—using real life experiences as teaching moments such as the act of using cash in the grocery store to demonstrate the value of money in a transaction. And the financial lessons continued over the last 12 years.
“Because it has always been just the two of us, we have a lot of discussions about opportunity cost—not necessarily using economic terms, but instead ideas. ‘If we did this, got this, spent this—then what would we be willing to give up.’”
When her daughter turned 15 last spring, she started her first part-time job at a local greenhouse. “She loves getting her email alert on paydays. She examines the hours, the taxes, and the amount sent to her savings account. She’s had a savings account for a long time, but now she can see how her actions affect the balance.”
Her daughter has also dabbled in buying stocks with the help of her uncle. “They decided on an amount to invest five or six years ago. She looked for businesses she believed in and purchased a handful of shares in several. She watches them and has seen the ups and downs in performance.”
Sarah’s perennial practice
As for Sarah, she continues to practice what she preaches “maybe to a fault,” she admits. “Sometimes I am a little too frugal. I do love a good garage sale!” Giving herself permission to splurge sometimes is maybe her greatest financial challenge. “I probably could loosen up and enjoy some spending, but my mindset has always been focused on the financial security side of life.”
Sarah set her path when she was a teenager, taking some of her earnings from summer jobs to open an IRA. Then, she opened a 403(b) when she started teaching and has continued to invest and increase her contributions over the years. Saving is second nature for her. “I feel a great sense of security when I open my statements, knowing that the money is growing and will eventually meet me when I need it.”
Her parents, who retired shortly after the 2009 interview after a combined 78 years of teaching, inspire her. “It is encouraging to see them enjoy a comfortable retirement because of their commitment to saving and investing for their future. It motivates me to stay on track.”
Sarah points to the purchase of her home as the most important financial decision she has made since we last talked. “I was able to buy a home in the neighborhood where I grew up. I’m proud that I managed a 15-year mortgage so it will be paid off in five more years.”
Looking to future seasons
This hard-line approach isn’t for everyone but it works for Sarah. As for her future? She will continue to sow financial literacy seeds at WDHS in and out of the classroom. “I want to grow the Youth Apprenticeship program to reach more students and allow for more opportunities in all career paths,” she says. This school year she doubled enrollment in the program and looks to continue that trend.
“Personally, the next big step for me will be helping my daughter take her next steps in education.” The contributions Sarah has been making to her 529 college savings plan will help with the cost, but you can be sure her daughter will be involved in the financial aspects of her higher education. It’s just how Sarah helps good things grow.
We’re here for you
Learn more about Member Benefits’ programs and services by calling 1-800-279-4030.
1 Stoddard, C. and Urban, C. (2018). The Effects of K-12 Financial Education Mandates on Student Postsecondary Education Outcomes.
2 Harvey, M. (2019) Impact of Financial Education Mandates on Younger Consumers’ Use of Alternative Financial Services. The Journal of Consumer Affairs.
6 things no one tells you about retirement
It’s to your benefit to prepare yourself now for some common financial considerations. After all, forewarned is forearmed.
Social Security benefits and retirement savings are taxable
You may not know that once you start collecting Social Security, Uncle Sam is going to want some of that money back. Withdrawals from a 403(b) or IRA will trigger taxes as well, unless you have Roth accounts. Take these taxes into account when you’re planning your retirement budget.
Healthcare costs may catch you by surprise
According to the Fidelity Retiree Health Care Cost Estimate, in 2020 an average retired couple age 65 needed approximately $295,000 saved to cover health care expenses in retirement. You will still have to pay premiums and co-pays once you’re on Medicare. And some services aren’t covered at all, like long-term care. Consider supplemental insurance and a long-term care insurance policy to help cover unplanned expenses.
You’re required to withdraw from your nest egg
You can’t keep retirement funds in your account indefinitely. You will need to start taking required minimum distributions (RMDs) from your retirement accounts generally at age 72 (or 70½ if you turned 70½ before January 1, 2020). If you don’t withdraw on time, you’ll pay 50% of the RMD amount not taken.
You may be retired for decades
A 65-year-old can expect to live another 19 to 21.5 years on average, according to the Social Security Administration. What’s more, one third of 65-year-olds will hit age 90, and 1 in 7 will live beyond age 95.
The prospect of a 20-year or more retirement and the increased chance of health care expenses with age mean you risk outliving your money. Be sure you plan accordingly. Meeting with a financial advisor at Member Benefits can help you balance out your risk and plan for the myriad of considerations that come with a longer life span.
Housing will remain your biggest expense
Many retirees work hard to pay off their mortgage so they can afford to travel or experience once-in-a-lifetime activities. But even if you pay off your mortgage by the time your retire, property taxes and the cost of upkeep can still take up a large chunk of your budget. U.S. households led by someone age 65 or older spent an average of $17,472 on housing in 2019 (MoneyTalksNews). Make sure you plan realistically for this continued expense.
Good news: You can keep saving for retirement
If you continue to work later in life, even part-time, you can still save in tax-advantaged retirement accounts. Consider saving at least enough to get any company match.
As of 2020, there is no age limit on making regular contributions to either Traditional or Roth IRAs. And if you are self-employed, you have a few other options. Visit irs.gov for more information.